Bankroll Allocation Techniques Employed by Leading Forecast Experts in High-Volume Event Markets
Eden Lange · Jun 15, 2026
Bankroll Allocation Techniques Employed by Leading Forecast Experts in High-Volume Event Markets
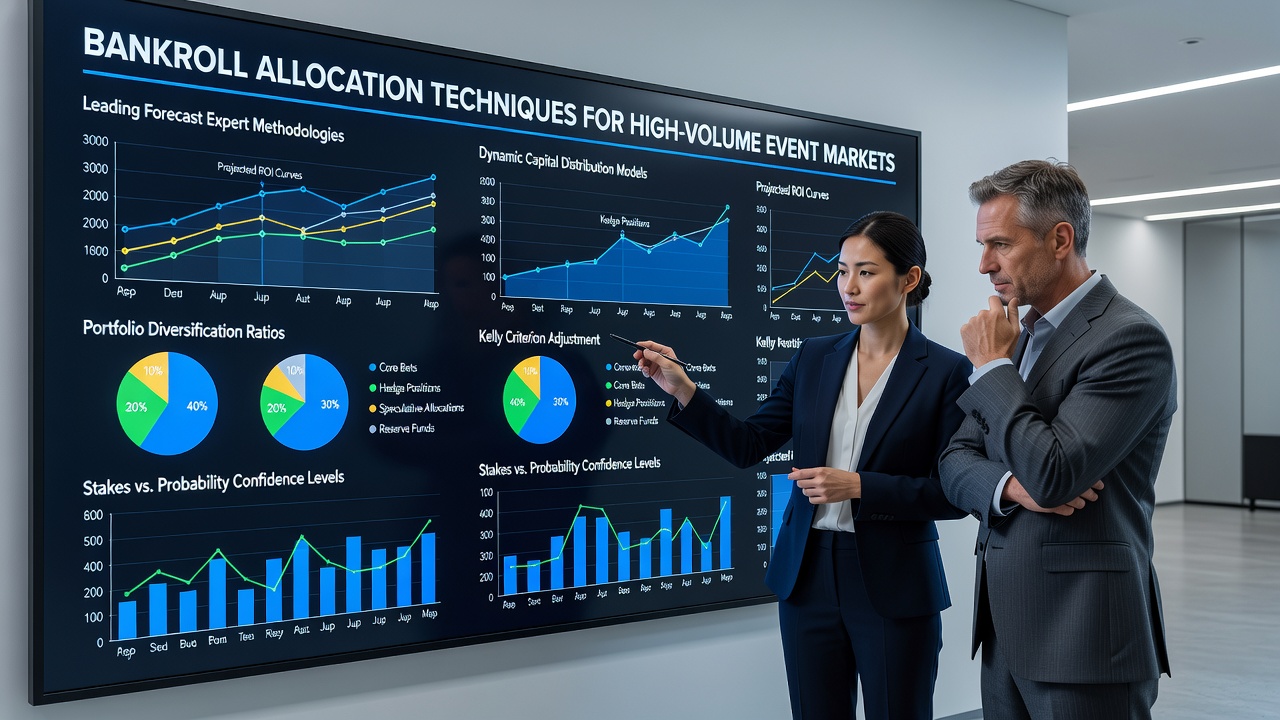
Leading forecast experts manage capital across numerous events each week by applying structured allocation rules that account for market volume, variance levels, and historical performance metrics. These specialists operate in environments where dozens of soccer matches, horse races, and tennis tournaments occur daily, requiring precise distribution methods that preserve capital while pursuing consistent returns. Data compiled through June 2026 shows increased activity in these markets, with experts adjusting percentages based on real-time liquidity and closing line movements reported by major exchanges.
Percentage-Based Distribution Methods
Experts apply percentage-based allocation by designating fixed portions of total capital to individual selections, typically ranging from one to three percent per position depending on assessed edge and market liquidity. This approach scales automatically with bankroll growth or contraction, maintaining proportional exposure even when event volume spikes during peak periods such as major racing festivals or grand slam tennis weeks. Observers note that this method prevents overcommitment during sequences of correlated outcomes, since each position remains tied to overall capital rather than absolute amounts.
Studies from the University of Nevada, Las Vegas Center for Gaming Research indicate that percentage systems reduce drawdown duration compared with fixed-stake approaches in simulated high-frequency environments. Experts further refine these percentages by incorporating factors like time between events and cross-market correlations, lowering exposure on overlapping fixtures where outcomes share common variables such as weather conditions or player fatigue.
Unit Sizing Frameworks in Practice
Many specialists divide capital into standardized units before assigning values to selections, creating a consistent measurement tool that translates edge estimates into position sizes. A unit might represent 0.5 percent of current bankroll, with stronger selections receiving two or three units while lower-confidence plays receive fractional allocations. This framework allows rapid adjustment when bankrolls fluctuate, since unit values recalculate at regular intervals rather than remaining static across extended campaigns.
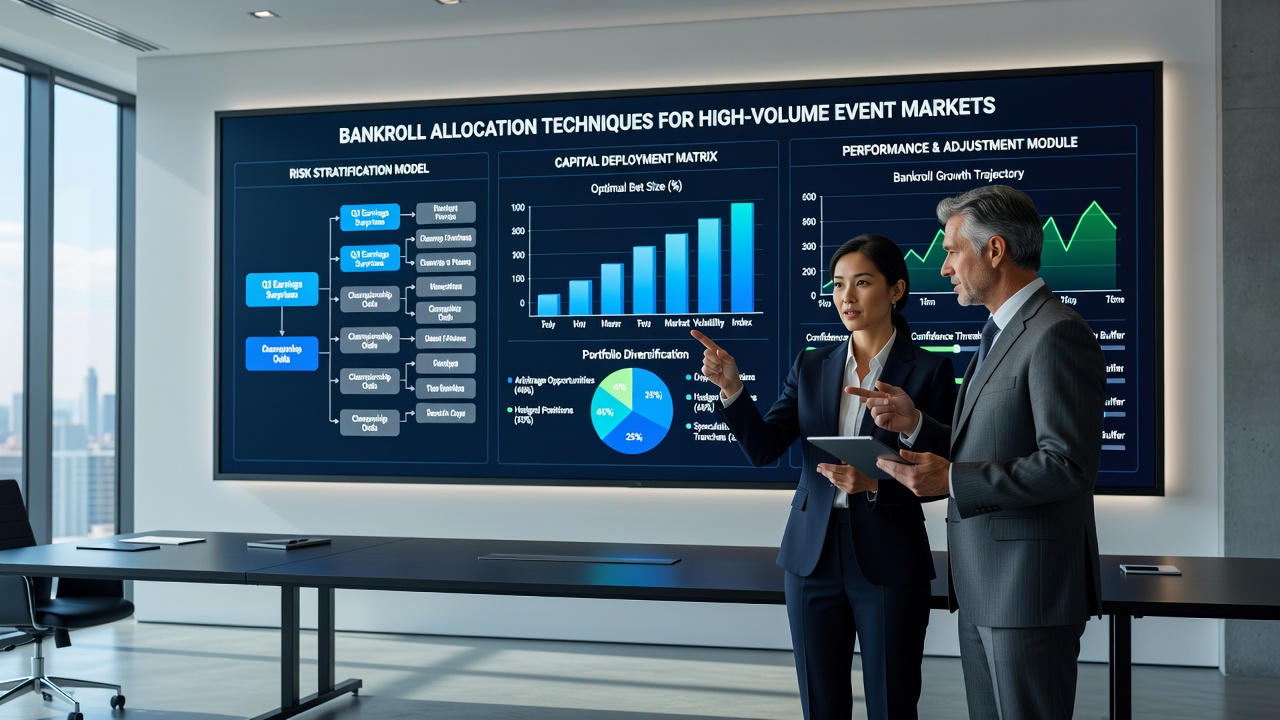
Those tracking performance through June 2026 report that unit-based systems help experts maintain discipline when volume increases, because decisions focus on unit counts rather than monetary figures that can trigger emotional responses. Software platforms used by professional forecasters automate unit recalculation after each settlement, incorporating results from soccer leagues, synthetic track racing, and challenger tennis circuits into unified portfolios.
Diversification Across Event Categories
High-volume specialists spread allocations across distinct categories to limit concentration risk, assigning separate capital buckets to soccer, racing, and tennis while enforcing internal limits within each bucket. This structure ensures that a cluster of unexpected results in one sport does not threaten positions in unrelated markets where independent edges may persist. Figures from the Victorian Responsible Gambling Foundation reveal that diversified allocation correlates with narrower monthly volatility bands among tracked professional accounts operating across multiple continents.
Experts adjust bucket sizes according to seasonal patterns, expanding racing allocations during summer turf seasons while increasing tennis exposure during indoor hard-court circuits. Rebalancing occurs at fixed calendar points, with surplus capital redistributed proportionally rather than held in cash reserves that could reduce overall yield during active periods.
Dynamic Adjustment Protocols
Protocols for dynamic adjustment allow experts to modify allocation percentages mid-cycle based on realized variance and updated edge calculations. When recent results produce larger swings than projected models anticipated, specialists reduce overall exposure by shrinking unit values or percentage targets until performance metrics stabilize. These adjustments rely on rolling performance windows rather than single outcomes, preserving responsiveness without overreacting to short-term noise.
Leading practitioners integrate liquidity data from betting exchanges into their protocols, decreasing stakes on selections where market movement indicates information asymmetry or reduced edge. June 2026 records show that experts employing such liquidity-aware adjustments maintained steadier equity curves compared with static allocation users during periods of elevated event density.
Conclusion
Bankroll allocation techniques used by leading forecast experts combine percentage scaling, unit frameworks, category diversification, and dynamic adjustments to navigate high-volume event markets effectively. These methods rely on measurable inputs and systematic recalibration, producing observable patterns in capital preservation and return consistency across soccer, racing, and tennis portfolios. Continued monitoring of regulatory and academic sources will likely refine these approaches further as data volume grows through subsequent seasons.